Compounded average
SOFR 30D
—
Awaiting official source observation
Debt and equity advisory for commercial real estate
Kiser Real Estate Capital advises owners and sponsors on commercial real estate debt and equity. We develop the capital strategy, identify suitable financing sources and coordinate the transaction through closing.
Checking official source observations.
Market benchmarks, not loan offers. Publishers update on business days; source dates may differ.
Sources: New York Fed · U.S. Treasury
© 2026 Federal Reserve Bank of New York. Content subject to its terms of use.
Who we are
We evaluate proceeds, loan term, recourse and prepayment provisions against your business plan and financing timeline.
We identify potential financing sources and prepare a focused submission around the property, sponsor and business plan.
We compare proposals, support term negotiations and coordinate underwriting and closing requirements with your transaction team.
Expertise
From a short-term bridge to a long-term hold, we evaluate financing around the asset, your investment strategy and the planned exit.
Start a ConversationDebt
Short-term financing for acquisitions, transitional assets and value-add plans, with attention to closing requirements and the path to permanent financing.
Debt
Financing for ground-up development, major renovation and adaptive reuse, evaluated against the project budget, schedule and exit strategy.
Debt
Long-term financing for stabilized properties, with loan structure and repayment terms matched to the ownership plan.
Debt
Financing across multiple properties, with attention to collateral requirements, release provisions and portfolio objectives.
Debt + Equity
Capital strategies for refinancing and recapitalization, including the relationship between senior debt and additional debt or equity.
Advisory
Guidance on financing alternatives, upcoming maturities and capital planning across the investment lifecycle.
Explore financing considerations across property types.
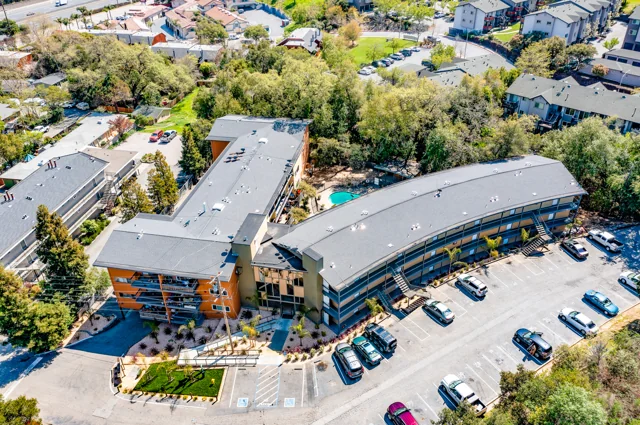
Financing for multifamily and residential income properties, with attention to occupancy, cash flow and the ownership plan.
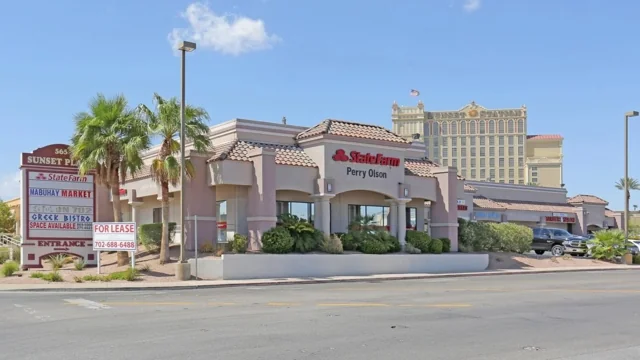
Financing for retail properties, evaluated around tenant credit, lease terms, occupancy and market position.
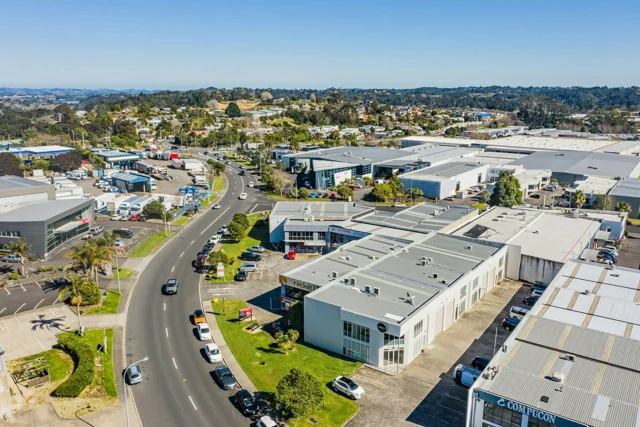
Financing for logistics, manufacturing and distribution properties, with attention to tenancy, building use and market demand.
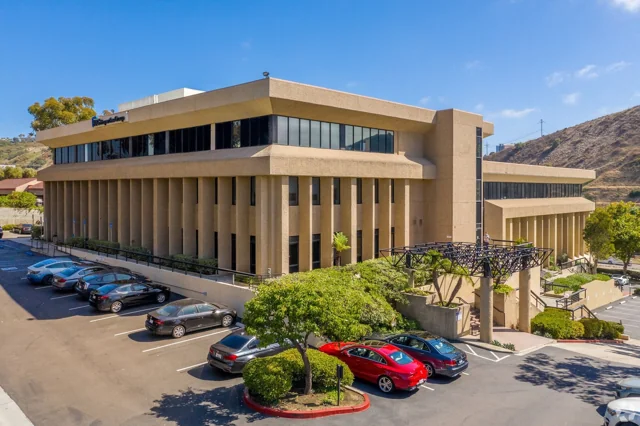
Financing for stabilized and value-add office properties, with attention to tenant strength, lease terms and market fundamentals.
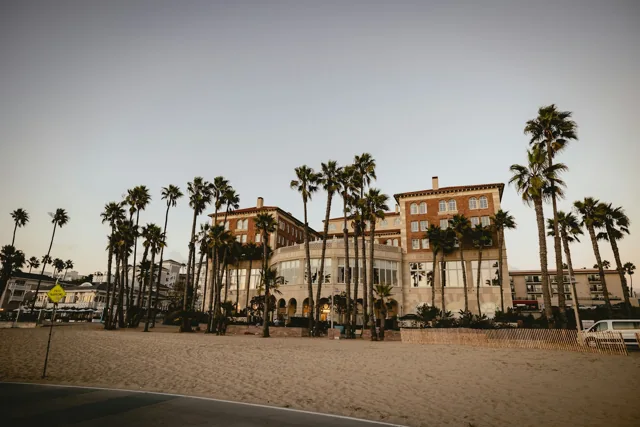
Financing for hospitality properties, evaluated around operating performance, management, brand affiliation and the business plan.
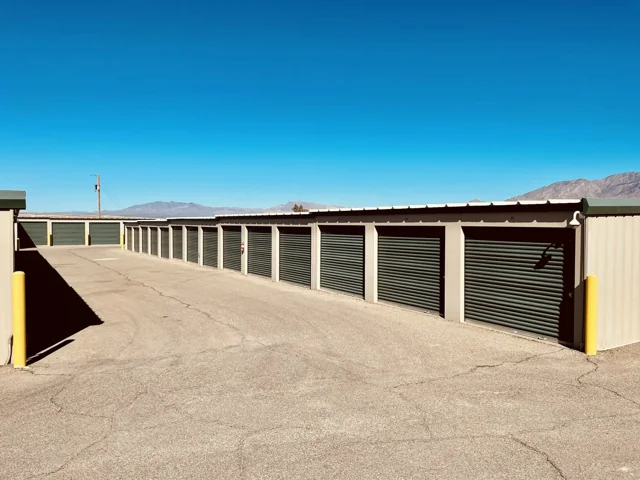
Financing for specialized property types, with attention to operating performance, collateral and lender requirements.
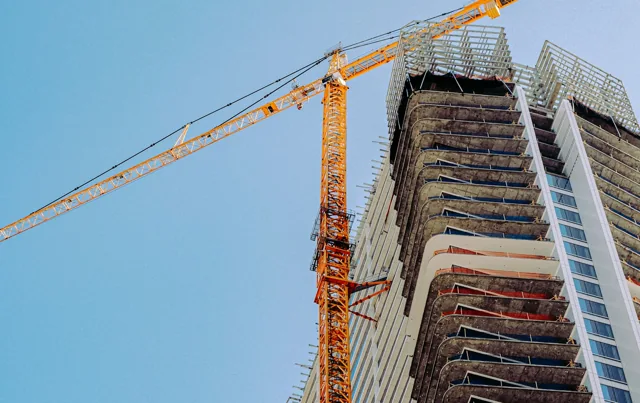
Construction and bridge financing evaluated against project costs, development milestones and the planned refinance or sale.
Process
A coordinated process connects the initial financing discussion, lender review and closing requirements.
Share the property type, financing objective and timeline. We identify the information needed to evaluate potential financing paths.
We evaluate potential financing structures and identify capital providers based on the asset, sponsor and business plan.
We coordinate lender submissions, compare proposals and support term negotiations and underwriting requests.
We coordinate lender, title, escrow and insurance requirements as the transaction progresses toward closing.
Compare more than the headline rate. Closing requirements, proceeds, covenants, recourse and exit flexibility all shape the capital structure.
Match the financing horizon to acquisition, repositioning, development or long-term ownership.
Review interest, fees, reserves, guarantees and prepayment alongside the proceeds.
Consider extension conditions, stabilization milestones and the path to refinance or sale.
Bring the property, the business plan and the timeline. We can help evaluate the financing options and next steps.
The Briefing
Plain-language notes on structuring, lender behavior and execution from the Kiser team.
Present the property, cash flow and business plan clearly so a lender can assess the request and identify key questions.
Read the briefing
Compare rate structure, amortization and prepayment provisions against your cash flow, holding period and planned exit.
Read the briefing
Start the conversation early enough to have choices. A practical timeline for owners with debt coming due.
Read the briefingContact
Send a brief overview of the property or the financing need. We can discuss potential financing structures, information needs and next steps.
For a time-sensitive transaction, call to discuss the deadline and financing objective.